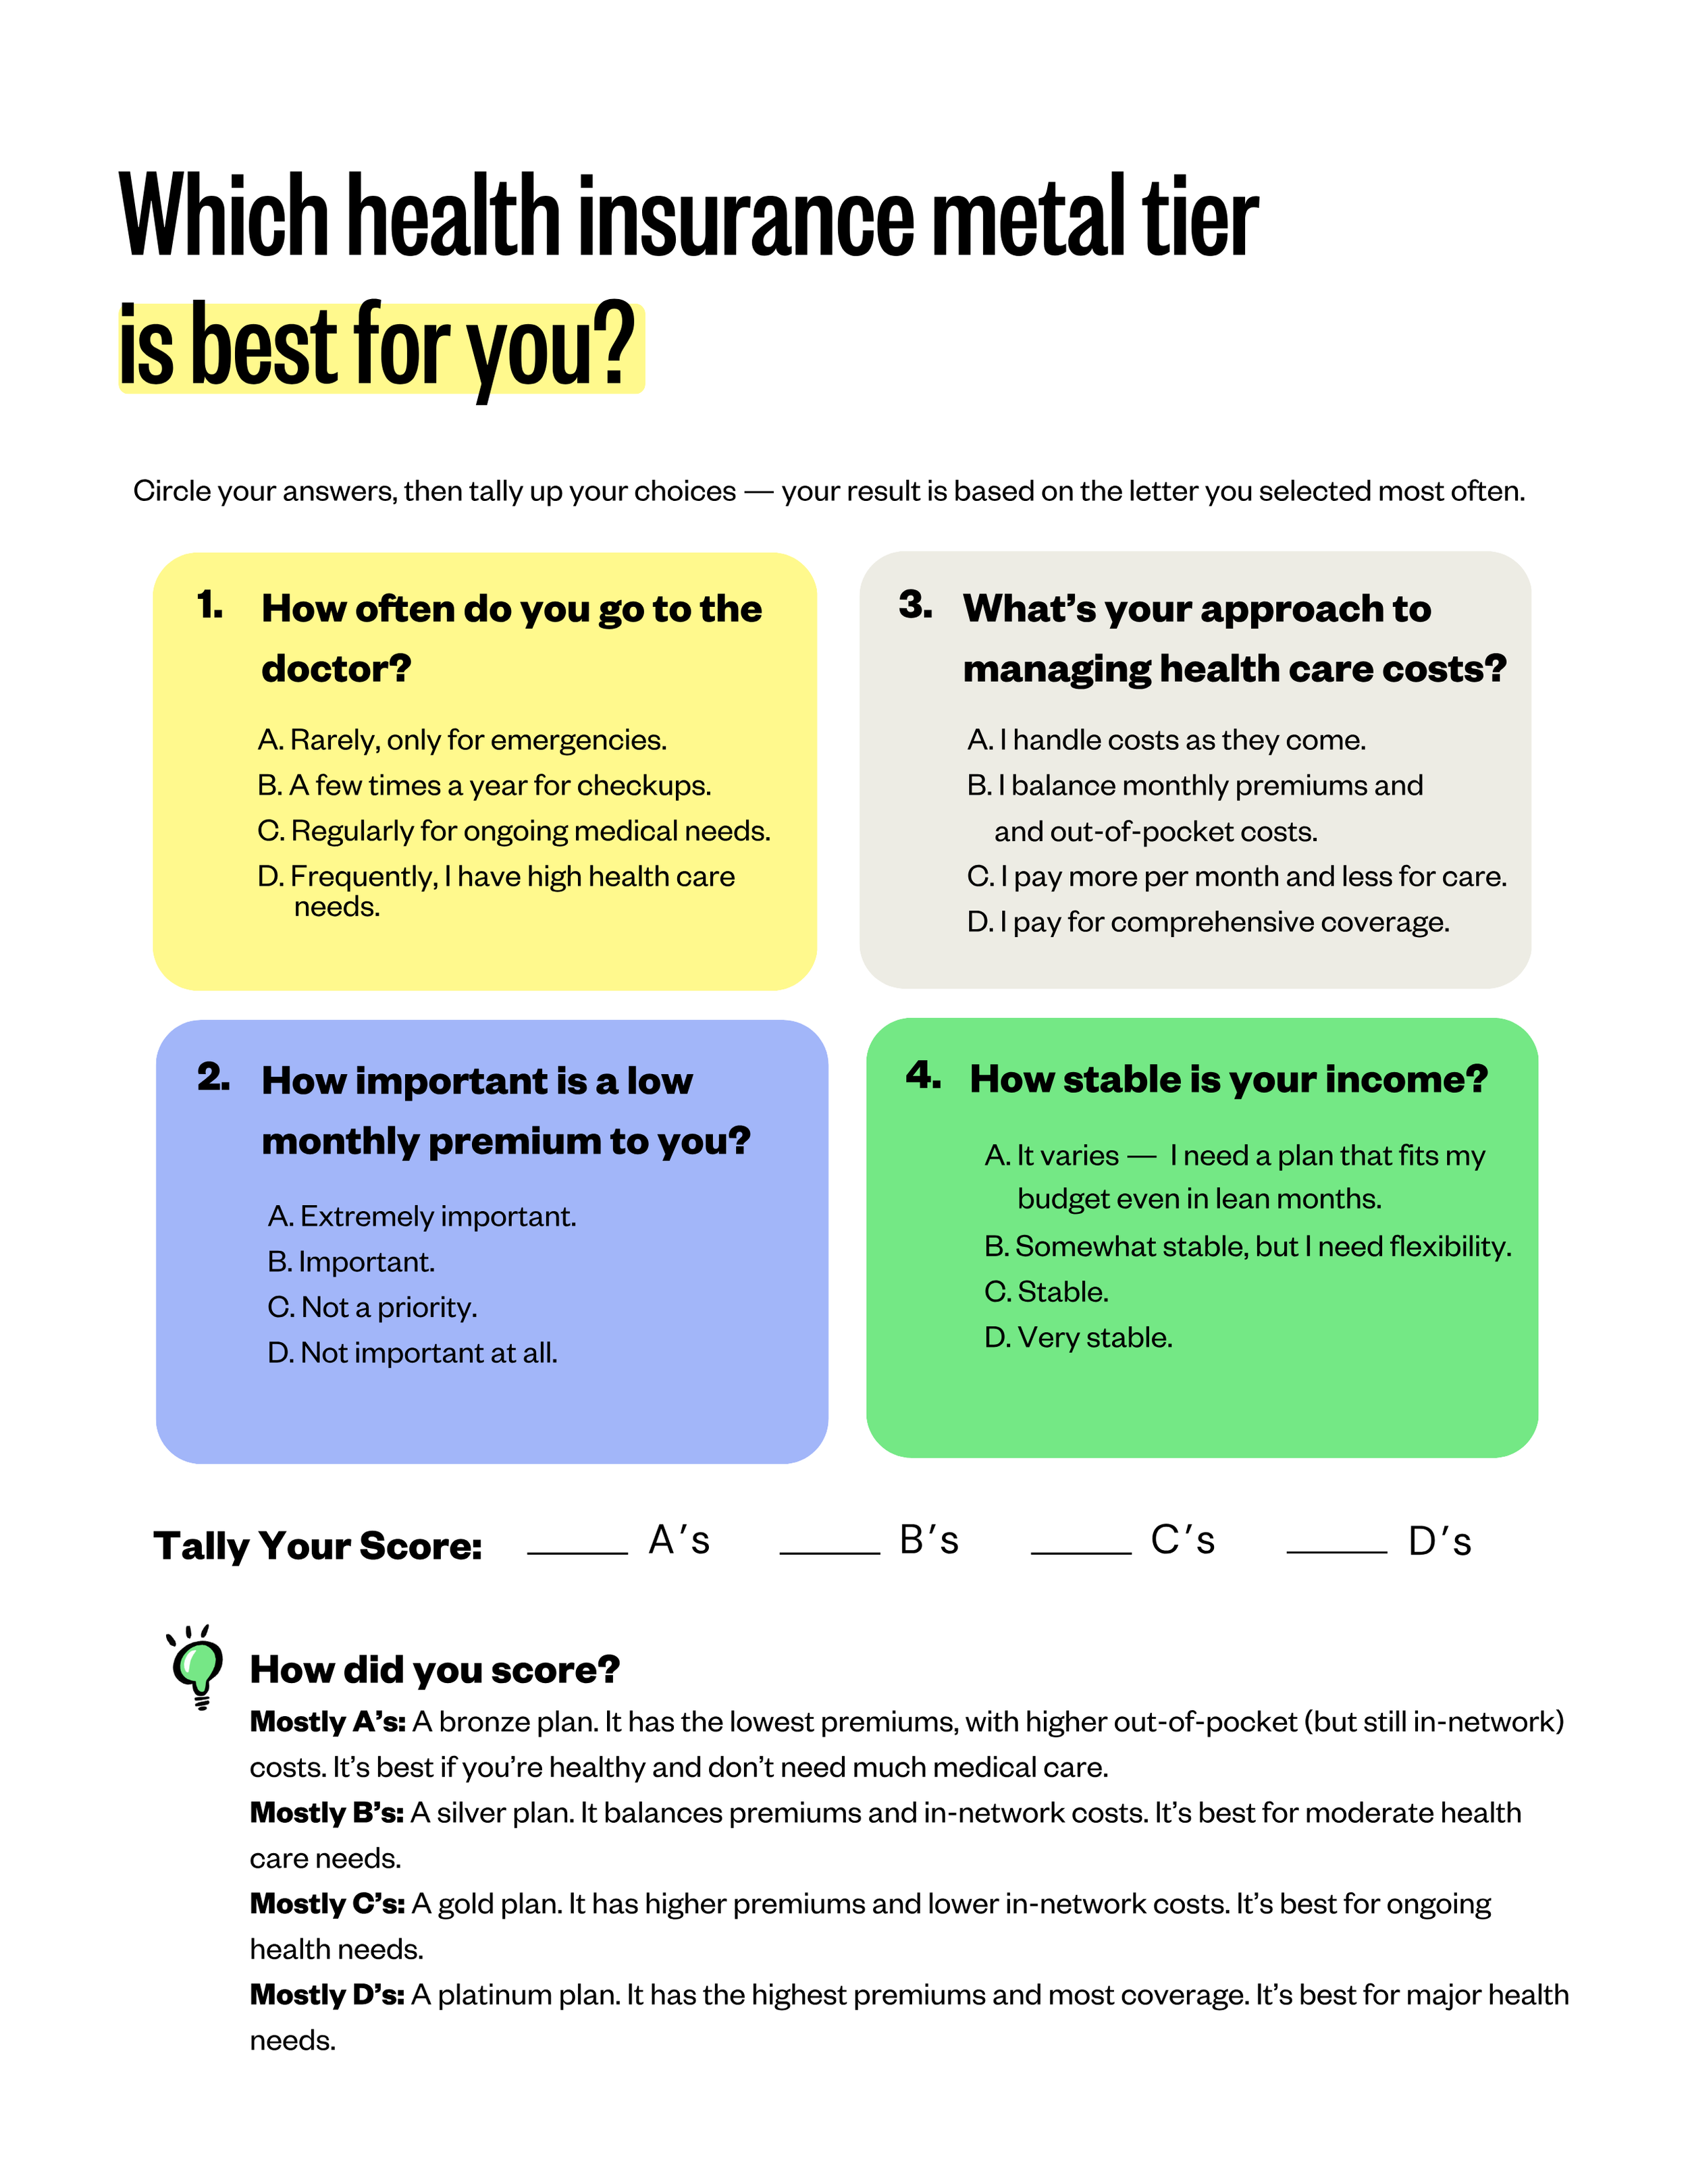
Choosing a health insurance plan can feel like pulling teeth — after all, there’s no “one size fits all” when it comes to buying coverage, because everyone has unique health care needs. To simplify the process, health plans are broken down into categories called metal tiers, which are plan categories that offer similar costs and levels of coverage. They are named in order of — you guessed it — the precious metals: bronze, silver, gold, and platinum.
The bronze plans have the least expensive monthly payments but offer the lowest amount of coverage, whereas platinum plans have the most expensive monthly payments but offer the greatest amount of coverage. Here’s a breakdown of each metal tier to help you pick the best option for you.
Want to compare metal tier plans near you? Enter your ZIP code below to get started.
Bronze
I like to compare health insurance shopping to buying a car. A bronze plan is like buying a used car with a bunch of mileage — this car is going to get you around town and cover your basic needs. However, it’s not the best for that big cross-country road trip, and it will cost you a lot when you need to repair it.
Bronze plans are best for people who don’t typically need or use health care. Are you looking for a yearly doctor’s checkup and maybe a prescription here or there? Maybe you just need minimal coverage that will prevent bankruptcy in case of an emergency? A bronze plan could be for you. The upside is that it will be cheaper upfront; the downside is that anything other than preventative care (think: a sprained ankle) is going to cost full price until you meet your deductible. Bronze plans often have deductibles of $7,000 or more, and in 2027 you could pay up to $12,000 out of pocket for one person. Before you choose bronze, ask yourself: could I pay that first big bill if something happened? If not, a bronze plan could leave you with coverage you can’t actually use.
Silver
A silver plan is like your minivan — it’s a solid choice, but not the most flashy. These plans cover more needs and will get you where you need to go. Silver plans typically have a lower deductible (that’s the amount you pay before your insurance coverage kicks in) and out-of-pocket maximum than bronze plans and start helping with prescriptions and doctor visits sooner.
If you use health care for more than just preventative care, but don’t have any major medical needs (such as surgery or disease maintenance), then a silver plan could be right for you. A lot of people miss this one. If your income is on the lower side, you may qualify for extra savings that lower your deductible and copays, and those savings only come with silver plans. Check what you qualify for with our subsidy calculator.
Gold
Next, a gold plan is that hearty pickup truck (or fuel-efficient Prius). This plan is going to be more expensive, but the benefits could outweigh the costs. It’s reliable, cost-efficient in the long run, and keeps you safe.
We recommend these plans for people who already know they have quite a few health care needs, like pregnancy or more intensive health maintenance. You’ll pay more on monthly premiums, but your deductible will be lower, and therefore you’ll end up paying less for surgeries or illnesses.
Platinum
Lastly, we have the platinum plan, which is kind of like driving a Tesla — it’s expensive upfront, and not necessary for everyone. But if you have it, you feel like you’re wearing an iron suit of protection. In the long term, it will give you the most coverage. However if you can afford the higher premiums and you know that you are going to need a lot of coverage, this plan could save you money in the long run.
Financial risk assessment
If you’re still unsure which plan is right, here’s a quick way to financially assess your risk between two plans. Say you’re deciding between a bronze plan with a $220 monthly payment and a $6,500 deductible and a silver plan with a $255 monthly payment and $1,500 deductible. These are example numbers, so your plan’s real cost will be different.
If you stay completely healthy, you’ll pay $420 less per year [ ($255-$220) x 12 ] with the Bronze plan. But, let’s say you hit your head playing flag football and visit the ER with a concussion. That ER visit could cost as much as $4,000. Under the bronze plan, you’ll pay the whole $4,000 out-of-pocket. With the silver plan, you’ll pay only your deductible of $1,500, and your insurance will help cover the rest. With that ER visit alone, you’d save $2,500 ($4,000 - $1,500) by choosing silver. Even after paying $420 more in premiums for the year, you’d still come out about $2,080 ahead.
Picking a plan comes down to your financial situation, your best guess on how much care you’ll need next year, and how much risk you’re comfortable with.
Happy health plan hunting! Not sure where to start? Take our plan quiz, or let us know if we can help you make your best decision. Otherwise, enter your ZIP code below to start comparing plans.